You can sell a house after a separation, but how depends on whose names are on the deed and the mortgage, and whether a court is involved. If you are married, you and your spouse will usually need to agree on the sale, or a judge will decide it for you. If you are unmarried co-owners, the deed decides. Either way, the sale goes smoothest when both owners agree on price, timing and who pays what until closing. This guide covers each step, from sorting out the paperwork to closing, and explains where a fast as-is cash sale fits.
TL;DR
- Check how title is held and who is on the mortgage before you do anything else. That decides who can sign and who stays liable.
- A divorce decree does not remove anyone from the mortgage. The lender only releases a borrower through a payoff, refinance or other change to the loan.
- Selling before or after the divorce is final is a legal and tax question. There is no universal answer, so talk to your attorney and a tax professional.
- If you need speed, no repairs and no showings, competing cash offers can close in about a week, and you can walk away if no offer works.
Table of Contents
- Start with the deed and the mortgage
- Your realistic options for the house
- The mortgage: the part people get wrong
- Before or after the divorce is final?
- Taxes to ask about before you sign
- How to sell after a breakup, step by step
- Selling fast or as-is: what to compare
- Perspective: why we built it this way
- Getting competing cash offers for a separation sale
- Special situations
- FAQ
- Sources
Start with the deed and the mortgage
Before you talk to a buyer or an agent, find two documents: the deed and the mortgage. They answer different questions.
The deed shows how you hold title. This matters more than most people expect. The American Bar Association explains that tenants in common can hold unequal shares and, generally, each can transfer their own interest without the other owner’s consent. That does not mean one owner can sell the whole house alone. In practice, a buyer or title company will want every owner’s signature before it insures a sale of the whole property. The form of title and state law both matter, so confirm with a Michigan attorney before assuming either of you can act alone.
The mortgage shows who owes the lender. The names on the loan and the names on the deed do not always match. Pull your latest statement, note the payoff amount, and ask the servicer for an official payoff figure. You need that number to know how much equity is really there.
If you are married
Until a court order says otherwise, marital property and debt generally remain jointly subject to division. A handwritten or informal separation agreement does not replace a court order. California’s courts say this in their guidance, and the principle applies broadly, though each state has its own rules.
In Michigan, property is divided by equitable distribution. That means fair, not automatically 50/50. A judge can depart from an even split but has to explain why.
Michigan also has a waiting period. According to one summary of Michigan divorce law, it is 60 days after filing for couples without minor children and six months when there are minor children. During that time the court can issue temporary orders about the use of property. That window is often when couples decide to sell.
If you are unmarried
A breakup between unmarried partners has no divorce court and no equitable distribution of a marital estate. Your rights come from the deed, the mortgage and any written agreement you made, plus general co-ownership law. If you cannot agree, the legal tool is partition, covered below.
Your realistic options for the house
The American Bar Association lists the standard outcomes: the home goes to one spouse, it is sold and the proceeds are divided, or the spouse with the children stays temporarily and a buyout or sale follows later. NerdWallet boils it down to three choices: sell and split, buy out the other owner, or keep joint ownership for a while.
| Option | Works best when | Main risk |
|---|---|---|
| Sell and split proceeds | There is equity and neither person can or wants to keep the house | You may have to move before you have a new place lined up |
| One owner buys out the other | One person can afford the loan alone and wants to stay | The remaining owner may not qualify on one income |
| Keep co-owning for now | Children are in school, or the market or interest rates are poor | Both of you stay on the loan and on the hook |
| Court-ordered sale | You cannot agree at all | Slower, costly, and you give up control of timing |
Keeping the house
A buyout does not always require a new loan. The Consumer Financial Protection Bureau reported that divorce does not necessarily require refinancing. Depending on the servicer and investor, you may be able to assume the existing mortgage or get a modification. The CFPB also found that some homeowners are pushed toward higher-rate refinancing they did not need. The person keeping the house still has to meet the lender’s underwriting standards.
If one spouse stays on a low-rate mortgage because the other cannot refinance, the American Bar Association advises writing a definite deadline or trigger for refinancing or listing the home. The agreement should also protect the borrower who moved out if payments are missed. Our guide on whether a divorce can force the sale of a house goes further on this point.
Deferred sale
Some couples keep co-owning until a child reaches a milestone, such as finishing school, or until one spouse can refinance. Experian describes this deferred sale approach, and it only works when both of you put in writing who pays the mortgage, property taxes, insurance, utilities and repairs. Without that, small disagreements turn into big ones.
When you cannot agree
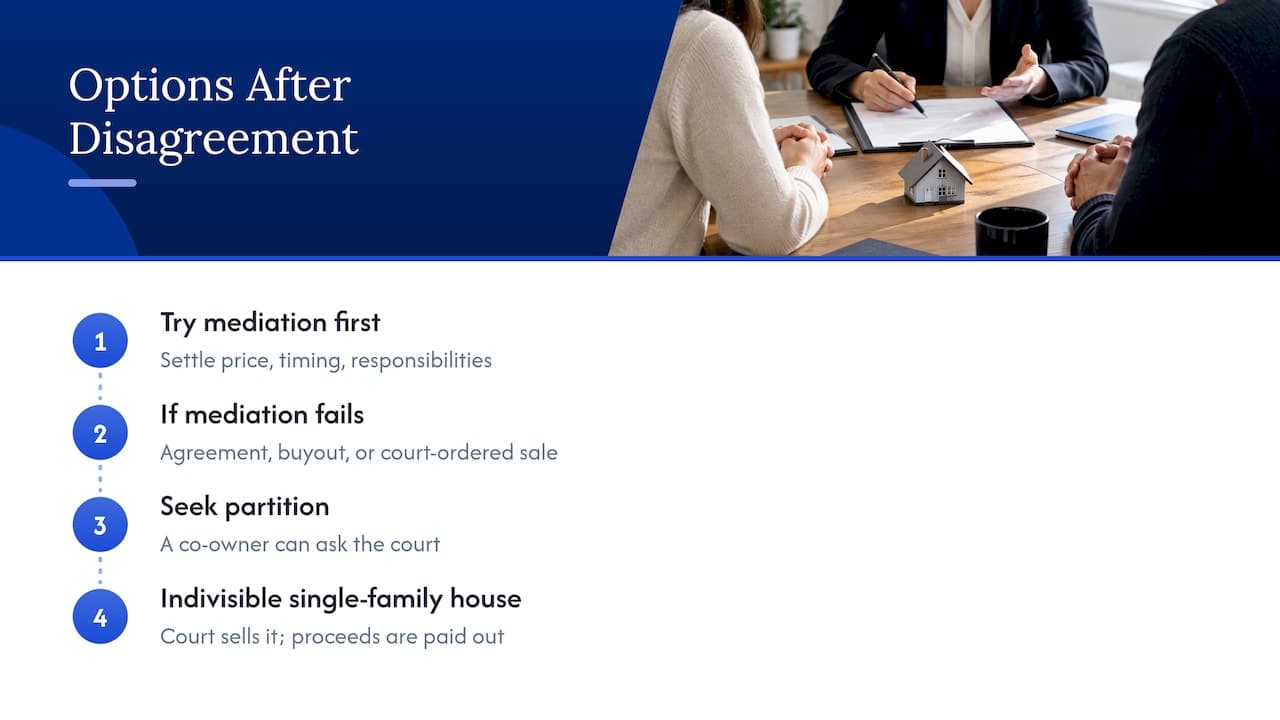
Try mediation first. It is cheaper and faster than court, and it can settle price, timing and who handles what. If that fails, any co-owner of land held in joint tenancy or tenancy in common can ask a court for partition. When the property cannot fairly be divided physically, as with a single-family house, it is sold through the court process and the proceeds are paid out. Massachusetts’ Land Court describes the same range: agreement, buyout or court-ordered sale. A court-ordered sale is usually the least attractive path because a stranger sets the timeline.
The mortgage: the part people get wrong
A divorce decree that gives the house and the loan to one spouse does not change your contract with the lender. The CFPB states that such a decree does not release the other spouse. While your name is on the loan, you stay liable unless the lender releases you or the loan is refinanced or otherwise changed.
The practical result: if your ex stays in the house and stops paying, the lender can come after you, and the missed payments can show on your credit. The ABA advises that the settlement provide for the home to be listed for sale if a payment is late. If you are behind already, read about selling to avoid foreclosure before the situation escalates, because options narrow once a sale date is set.
Until closing, agree in writing on who pays what. The list is short: mortgage, property taxes, homeowner’s insurance, utilities, lawn and snow, and any repair that comes up. Keep records of every payment. They matter when proceeds are divided.
Before or after the divorce is final?
There is no universal best time. Selling before the final judgment turns the house into cash and can make the property division simpler. Waiting can give you housing stability, or time to refinance. The IRS addresses the tax side in Publication 504, and the right call depends on legal authority, mortgage exposure, your children’s needs, the market and the tax rules. Your divorce attorney and a tax professional should look at your specific numbers.
A few practical points favor selling sooner:
- Carrying costs keep running. Every month adds mortgage interest, taxes and insurance, and often two households’ rent or utilities.
- Equity is a known number. A sale replaces an appraisal argument with a real price.
- Neither of you is tied to the other’s credit. Once the loan is paid off, the liability ends.
Points that favor waiting: the children’s school year, a refinance that is realistic within months, or a market you expect to improve. Those are judgment calls, not guarantees.
Taxes to ask about before you sign
This is general information, not tax advice. Three federal ideas come up most often, all covered in IRS Publication 504:
- Capital gain. Gain is generally the sale price minus selling costs and your tax basis. Basis commonly includes what you paid plus qualifying improvements.
- The home sale exclusion. An individual may exclude up to $250,000 of gain on a principal residence, and eligible joint filers up to $500,000. Eligibility depends on ownership, residence, filing status and prior use of the exclusion.
- Transfers between spouses. A transfer between spouses, or former spouses when incident to divorce, generally produces no recognized gain or loss. But a buyout that is not taxed now can still lead to taxable gain when the person who kept the house later sells to a third party.
Timing can change which exclusion you qualify for, so ask a CPA before you pick a closing date. We explain the basics in our guides to the home sale exclusion in a divorce and keeping the $500,000 exclusion in Michigan. State tax and reporting rules can apply too.
How to sell after a breakup, step by step
- Gather the documents. Deed, mortgage statement, a payoff letter, recent tax bill, insurance policy, and any separation or settlement papers.
- Get legal guidance. A Michigan family law attorney tells you who must sign and whether a court order is needed. For a divorce, ask whether the judgment or a temporary order controls the sale.
- Agree on terms in writing. Who handles the sale, the minimum price you will each accept, how proceeds are split, and who pays costs until closing.
- Choose how to sell. A traditional listing, a sale to a single investor, or competing cash offers. More on this below.
- Compare offers on net proceeds. Not just the headline number.
- Open escrow with the title company. The title company confirms ownership, pays off the loan and disburses proceeds. Divorce attorneys often draft the escrow terms, so send the agreement to yours.
- Close, then settle up. Payoff, closing costs, then the remainder is divided as agreed or ordered.
For a Metro Detroit example of the legal steps, see our guide to a Sterling Heights divorce sale. Our page on selling a house during divorce in Michigan covers the full process.
Selling fast or as-is: what to compare
A traditional listing means prep, cleaning, showings and waiting for a buyer’s financing. That is hard when two people are splitting up, one may have already moved out, and the house may need repairs neither of you wants to fund. A cash sale removes most of that. The main variable is how many buyers you hear from.
When you compare offers, line them up on these points:
- Net proceeds after all costs. Ask what fees, if any, come off the price at closing.
- Closing date and flexibility. Can the buyer close when both of you are ready, not just quickly?
- Contingencies. Financing, inspection and appraisal contingencies are the most common ways cash deals fall apart.
- Condition terms. Confirm the offer is truly as-is, with no repair requests after inspection.
- Proof of funds. Ask for it.
- Obligation. You should be able to decline every offer without penalty.
With two sellers, add a practical check: both of you need to see the same offers at the same time, so nobody feels the other negotiated behind their back. Our piece on the role of competing cash offers explains why several bids tend to put more money on the table than a single one.
Perspective: why we built it this way
Most separation sales we see have the same shape. Two people want the same thing, which is to be done, but they are tired, and they distrust each other’s numbers. A single investor’s offer makes that worse. One person thinks it is too low, the other wants it over with, and nobody can prove either view.
That is why HouseGoodbye is not one cash buyer. Several vetted local buyers bid on the same house, you both see every offer, and the numbers settle the argument that words could not. There are no commissions, no repairs and no showings, and you owe nothing if you decline. Our typical close is about 7 days, compared with roughly 73 days on the MLS, which matters when two households are running on one house’s costs.
One caution from experience: do not let speed push you past the paperwork. Get your attorney’s sign-off on who may sign and how proceeds are split before you accept an offer. A fast sale on a bad agreement is still a bad outcome.
— Bryan
Getting competing cash offers for a separation sale
If you and your co-owner have agreed to sell and want a clean, quick exit, we can help. Enter the address and local vetted buyers bid on the house as-is, anywhere in Michigan, from Detroit and Warren to Grand Rapids, Flint and Lansing. You compare the offers and either accept one or walk away.
See how it works on our cash home buyers page, or go straight to selling your house fast for cash. If the house needs work, has a code violation or has sat vacant since one of you moved out, the as-is sale page explains what we take on.
Special situations
One of you has moved out. The vacant house still needs insurance, utilities and upkeep. Settle who pays, and tell the insurer if the home is unoccupied, since policies often limit coverage for vacant properties.
You need to buy another home at the same time. Timing a purchase around a sale is its own puzzle. Our guide on selling while buying another home walks through the options.
A job change forces a move. If a relocation or start date drives the schedule, see how to coordinate the sale with a job start date.
The house is a rental with tenants. Tenants’ lease rights usually continue through a sale, so tell any buyer about the lease up front.
FAQ
Can I sell the house without my ex’s signature?
Usually not the whole house. Title companies generally want every owner to sign, and a married couple’s property is subject to division by the court. A tenant in common can sometimes transfer only their own share, but that rarely produces a usable sale. Ask a Michigan attorney about your title and, if needed, a court order.
Am I still responsible for the mortgage after we separate?
Yes, if your name is on the loan. The CFPB says a divorce decree assigning the mortgage to your ex does not release you from the lender’s claim. You are released when the loan is paid off, refinanced or changed by the lender.
Should I sell before the divorce is final?
It depends. Selling first can simplify the division and end the shared mortgage risk, while waiting can protect housing stability or allow a refinance. Your divorce attorney and a tax professional should compare both paths using your numbers, including the home sale exclusion.
How fast can a separated couple sell for cash?
On our platform, a typical close is about 7 days after you accept an offer, versus roughly 73 days on the MLS. The real timeline also depends on payoff, title work and any court approval you need, so line up your paperwork first.
What if we cannot agree on whether to sell?
Try mediation first. If that fails, a co-owner can ask a court for partition, which can end in a court-ordered sale. It is slower and gives you less control over timing and price than agreeing on a sale yourselves.
Sources
- Property and debts in a divorce, California Courts
- Understanding the Forms of Title in Real Estate for Family Law Practitioners, American Bar Association
- Separating Property, American Bar Association
- How to Split a House in a Divorce, NerdWallet
- Homeowners face problems with mortgage companies after divorce or death of a loved one, CFPB
- The Favorable Interest Rate Mortgage as Marital Asset, American Bar Association
- What to Do With the House in a Divorce, Experian
- Partition, Legal Information Institute
- Frequently asked questions about partition cases, Massachusetts Land Court
- Can a debt collector contact me about a debt after a divorce? CFPB
- Publication 504, Divorced or Separated Individuals, IRS
- Capital Gains Tax on Your Family Home During Divorce, DivorceNet
- Divorce Laws in Michigan
- Property Asset Division in Michigan