If your property taxes are delinquent, your fastest paths are the same two every Michigan homeowner has: get an approved payment plan with your county treasurer, or complete a fast cash sale that pays off the tax debt at closing. HouseGoodbye connects Michigan sellers with competing cash buyers who can close in days, not months, which matters when a forfeiture deadline is closing in.
TL;DR:
- Paying off delinquent property taxes through a cash sale typically requires verifying the exact payoff amount from the county treasurer before negotiating a sale.
- Michigan’s property tax forfeiture process spans three years, with fees and interest increasing the debt and reducing time to prevent foreclosure.
- A quick cash sale can close within one to two weeks if the buyer provides proof of funds and handles the tax payoff directly through escrow.
- Getting a current, written payoff statement early is crucial to avoid surprises during closing, especially for dealing with liens and excess proceeds.
- Homeowners facing imminent foreclosure should sell immediately or seek hardship options, while those with more time should explore payment plans and official hardship relief programs.
Table of Contents
- Sell House With Back Taxes Michigan: Where to Start Today
- Michigan’s Tax Foreclosure Timeline: What Deadlines Are You Facing?
- How to Sell Fast With Back Taxes and Actually Close
- What Happens to Liens and Sale Proceeds at Closing?
- How HouseGoodbye Helps Michigan Sellers Facing Back Taxes
- When to Sell Now vs. When to Ask the Treasurer for Time
- Ready to Compare Cash Offers on Your Michigan Home?
- Where to Get Official Guidance Next
- Sources
- FAQ
Sell House With Back Taxes Michigan: Where to Start Today
The first move isn’t listing your house or calling a real estate agent. It’s calling your county treasurer’s office, the same day if you can.
County treasurers handle delinquent property tax accounts directly, and most will tell you exactly where you stand if you ask the right questions. Request your exact payoff amount in writing, not a verbal estimate that could be outdated by the time you act. Ask whether you qualify for a payment plan, and ask specifically about hardship provisions, since some counties, like Kent County, publish financial hardship guidance that spells out eligibility and how to apply.
Before you call, gather what the treasurer’s office and any future buyer will ask for:
- Your deed or property tax identification number
- The last two years of tax bills and any delinquency notices
- Current mortgage statement, if you have one
- Government-issued ID
- Estate or probate documents, if the property came through inheritance
If forfeiture or foreclosure is close, ask the treasurer for a written statement of the exact amount required to stop the process. That same letter is what a title company or a cash buyer will use to confirm the payoff at closing, so getting it early saves you a step later.
Pro Tip: Ask the treasurer’s office if they can email the payoff letter instead of mailing it. A same-day PDF can shave a week off your timeline when you’re racing a foreclosure judgment date.
Michigan’s Tax Foreclosure Timeline: What Deadlines Are You Facing?
Michigan runs its property tax delinquency process on a fixed three-year cycle, and missing any point on it moves you closer to losing the property outright. Unpaid taxes are returned delinquent on March 1 of the following year. If they’re still unpaid a year later, the property is forfeited to the county treasurer on March 1 of year two. Foreclosure judgment becomes effective March 31 of year three, according to the Michigan Department of Treasury.
That’s a real three-year runway, but most of it gets eaten up by fees and interest that make the payoff grow every month you wait.
Typical charges that stack onto the original tax bill include:
- A 4% administrative fee added at delinquency
- 1% monthly interest, noncompounded, on the unpaid balance
- A title-search fee (for example, a typical fee for some counties is $175) once the file enters forfeiture
- Recording fees and, in some counties, a site-visit fee
Once a foreclosure judgment is entered, the redemption window effectively closes, and title can vest with the Foreclosing Governmental Unit if the balance is not paid in full in time. MCL 211.78k also gives circuit courts limited authority to withhold a property from foreclosure in hardship cases, including for minor heirs or legally incapacitated owners, sometimes for up to a year.
Getting a current, written payoff statement from your treasurer is the only way to know your real number, since interest resets the balance every month.
How to Sell Fast With Back Taxes and Actually Close
A cash, as-is sale is often the fastest route out of a tax delinquency, since an investor buyer generally does not require repairs, staging, or cleaning, and the purchase contract can direct the tax payoff directly from escrow at closing. That removes the two things that usually slow a sale, financing contingencies and repair negotiations, from the equation entirely.
A traditional MLS listing with an agent can still work if you have months of runway left before forfeiture. But it comes with real tradeoffs: time on market, buyer financing delays, inspection repair requests, and commission costs that eat into your net. If a foreclosure judgment date is approaching, that timeline usually doesn’t fit.
Here’s a sequence that keeps a sale moving fast:
- Get your payoff letter. Request a written, dated statement from the county treasurer showing the exact amount owed.
- Order a title search or preliminary title commitment. This surfaces any other liens, mortgages, or judgments before a buyer’s title company does, so there are no surprises at closing.
- Request multiple written cash offers. Compare them side by side, not just on price but on how each handles the tax payoff.
- Require escrowed tax payoff language in the purchase contract. The buyer’s funds should cover the delinquent balance directly through the closing agent, not through you.
- Verify proof of funds. Ask for a bank letter or verification of funds before you take an offer off the table.
- Schedule closing. A serious cash buyer can typically close within one to two weeks once title work is done.
Pro Tip: Never accept a cash offer that doesn’t specify who pays the treasurer and when. “We’ll handle the taxes” is not a contract term. Get it in writing, tied to a closing date.
What Happens to Liens and Sale Proceeds at Closing?
Tax liens sit at the top of the payoff line. When a sale closes, the title or escrow company typically pays the county treasurer directly from the sale proceeds before any money reaches you, which is exactly why a current payoff statement matters so much going into closing.
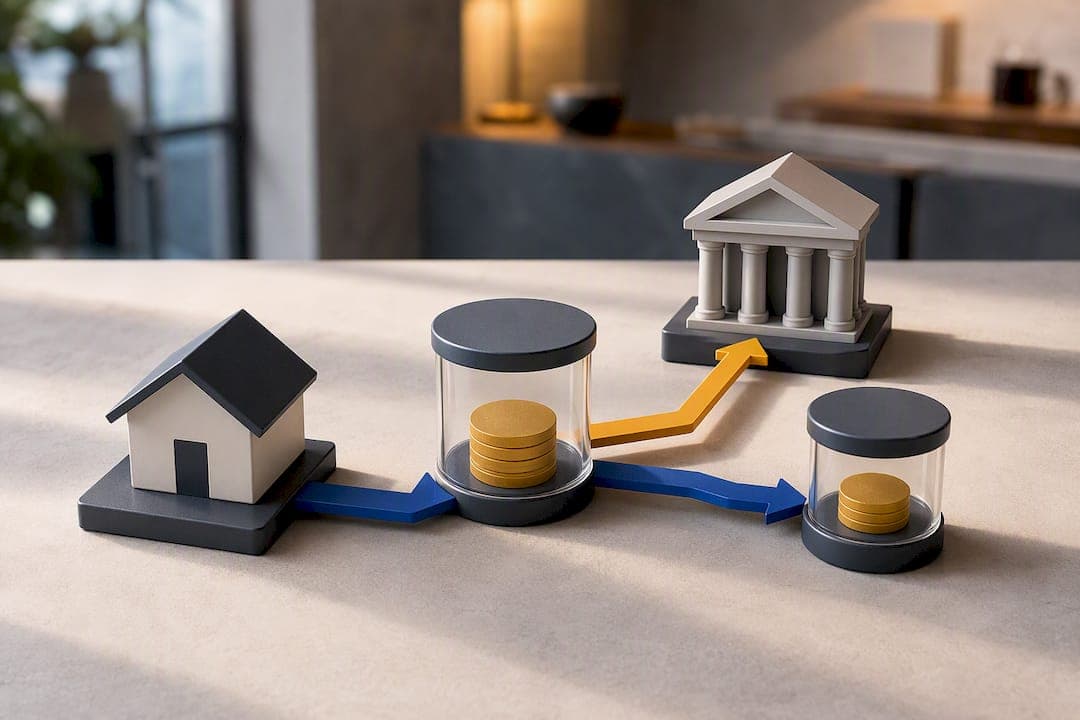
Other liens can complicate this picture. The Michigan Department of Treasury notes that state tax debts can also generate liens through its Collections Services Bureau, separate from local property tax delinquency, and both types need to be resolved before or at closing.
Costs that typically come out of your proceeds include:
- The delinquent tax balance plus accrued interest and administrative fees
- Recording and title fees
- Any site-visit fees the county has already assessed
- Standard closing costs, such as title insurance and settlement fees
If a sale doesn’t fully absorb the payoff and any excess remains, some counties allow former owners to file a claim for excess proceeds within a statutory window, though the rules and deadlines vary by county. Ordering a title search as early as possible is the single best way to know what you’re actually working with before you negotiate a price.
How HouseGoodbye Helps Michigan Sellers Facing Back Taxes
Housegoodbye works by putting your property in front of multiple vetted local investors at once, who then compete for it with real cash offers rather than one lowball number. You can sell your house as-is, skip repairs, staging, and agent commissions, and compare bids side by side before choosing one.
Before you accept any offer, whether it comes through HouseGoodbye or elsewhere, ask each buyer:
- Who pays the county treasurer at closing, and how is that documented?
- Can you provide written proof of funds?
- What’s your realistic closing timeline, in days?
- Which title or escrow company will handle the transaction?
Getting straight answers to those four questions is what separates a buyer who can actually close from one who’s still shopping for financing.
When to Sell Now vs. When to Ask the Treasurer for Time
If a foreclosure judgment date is close and you can’t realistically raise the full payoff, sell now. If you’re a year or more out and might qualify for a payment plan or hardship relief under MCL 211.78k, call the treasurer first. Speed usually costs you some sale price, but it beats losing the house to the county outright.
— Bryan
Ready to Compare Cash Offers on Your Michigan Home?
This service is the alternative to a single lowball cash buyer knocking on your door. It puts several vetted local investors in competition for your property at once, so you see real, comparable numbers instead of one take-it-or-leave-it offer, without paying agent commissions or fixing anything first.
Getting started takes three steps: submit your property details, review the competing cash offers as they come in, and confirm which buyer will handle the tax payoff directly through escrow before you sign anything. Ask each bidder for a written closing timeline and proof of funds before you commit. If your tax deadline is close, request offers through the Sell Your House Fast page now rather than waiting for a treasurer response that may take days you don’t have. If your home is part of an estate, the inherited house sale option covers that situation directly. And if you need a hand managing money and bills while your sale closes, Savings Grove’s homeowner money tips offer practical, non-real-estate guidance worth a look.
Where to Get Official Guidance Next
- Michigan Department of Treasury forfeiture and foreclosure page: confirms exact statutory deadlines
- MCL 211.78k: governs hardship petitions and redemption
- Kalamazoo County’s tax foreclosure timeline: shows real county fee examples
- Kent County’s hardship guidance: outlines local payment-plan eligibility
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Property tax forfeiture and foreclosure — Michigan Department of Treasury
- MCL 211.78k — Michigan Legislature
- Tax Foreclosure Timeline — Kalamazoo County, MI
FAQ
Can I Sell My House With a Tax Lien in Michigan?
Yes. A tax lien doesn’t stop a sale, but it does need to be paid off at closing, usually straight out of escrow before you receive any proceeds. Getting a current payoff statement from your county treasurer before you list or accept an offer avoids surprises at the closing table.
How Fast Can I Sell a House With Back Taxes in Michigan?
A cash, as-is sale can often close in one to two weeks once title work is done, compared to months for a financed MLS sale. Housegoodbye connects sellers with competing cash buyers who can typically close in as little as seven days once a payoff letter and title search are in hand.
What Happens if I Don’t Pay Property Taxes in Michigan?
Unpaid taxes become delinquent, then forfeit to the county treasurer, then move toward a foreclosure judgment over a three-year cycle, per the Michigan Department of Treasury. Once judgment is entered, redemption effectively ends and title can transfer to the county.
Does HouseGoodbye Charge Homeowners a Fee to Sell?
Housegoodbye’s current pricing and program details are listed on its site, and homeowners compare offers directly from competing investors with no obligation to accept any bid. There’s no cost to submit a property and review the cash offers that come back.
Can the County Treasurer Give Me More Time to Pay?
Some counties offer payment plans or hardship consideration, and courts have limited authority under MCL 211.78k to withhold a property from foreclosure in specific circumstances. Contact your treasurer’s office directly and ask in writing what you qualify for, since eligibility varies by county.