If you need to sell your Madison Heights or Detroit-area house because of a relocation, the fastest reliable path is a localized multiple-offer cash marketplace like a localized multiple-offer cash marketplace which surfaces competing investor bids and can close quickly according to its stated timeline. Expect an as-is sale, so no repairs or staging, but you still owe Michigan disclosure paperwork and transfer-tax filings. Start now by pulling together your seller documents and requesting bids today.
TL;DR:
- Most fast cash closings in Detroit take between 7 and 21 days, with closings as quick as 7 days possible for homes without mortgage or tenant issues.
- Proper documentation, including proof of ownership, payoff details, tax bills, and a relocation timeline, is essential to secure firm bids and avoid delays.
- The highest bid may not net the most profit because buyers’ credits, closing costs, or liens can significantly reduce the net amount, making verification critical.
- Michigan law requires full disclosure of known defects before closing, and late or incomplete disclosures can give buyers an exit option, especially on tight timelines.
- Verifying wiring instructions by phone and following CFPB scams advice is crucial to prevent wire fraud during fast closings.
Table of Contents
- What Makes a Relocation Home Sale in Detroit Different
- Seller Packet: Documents and Details to Prepare Before You Request Bids
- How Do You Compare Multiple Cash Offers?
- Timeline Expectations for Fast Closings (7 to 21 Days)
- Michigan Seller Disclosure Requirements You Can’t Skip
- Transfer Tax and the Property Transfer Affidavit: What You’ll File
- Wire Fraud and Closing Fund Safety Steps
- What Does Selling a House in Detroit Actually Cost?
- Do You Need to Stage a House You’re Selling As-Is?
- How Detroit’s Market Trends Affect Your Price and Speed
- Should You Use a Real Estate Agent for a Detroit Relocation?
- Legal Considerations Specific to a Detroit Relocation Sale
- Coordinating Your Home Sale with Your Moving Timeline
- The Practical Lessons Relocation Sellers Learn the Hard Way
- Get Multiple Cash Offers Fast Through Housegoodbye
- Sources
- FAQ
What Makes a Relocation Home Sale in Detroit Different
A relocation sale runs on a deadline you didn’t set for real estate reasons. Maybe your employer gave you six weeks to report to a new office, or your lease at the next stop starts on a fixed date no matter what your Madison Heights house does. That changes the math entirely. A homeowner with no deadline can list, wait for the right buyer, and negotiate repairs over weeks. A relocating seller doesn’t have that luxury.
This is where relocation assistance Detroit programs and competing cash-offer marketplaces earn their keep. Instead of a single buyer who can walk away after an inspection, you get several investors bidding against each other, which shortens the timeline and gives you leverage you wouldn’t have with one offer sitting on the table. The trade-off is that as-is buyers price in the condition of the home, so the highest number isn’t always the smartest pick, a point worth remembering before you compare bids.
Detroit’s real estate market also moves differently than suburban Michigan overall, with older housing stock, more probate and inherited-property sales, and a wider range of buyer types actively bidding on distressed or dated homes. That variety works in a relocating seller’s favor, because more active buyers means faster competing offers.
Seller Packet: Documents and Details to Prepare Before You Request Bids
Investors move fast when you hand them everything at once. A scattered paper trail is the single biggest reason a “close in 7 days” promise turns into three extra weeks of back-and-forth. Build this packet before you request a single bid.
- Photo ID matching the name on the deed.
- Deed or proof of ownership, pulled from your closing packet or the Wayne or Oakland County register of deeds.
- Mortgage or HELOC payoff contact, including loan number and a direct phone line to the servicer.
- Current property tax bill showing any unpaid balance.
- Utility status, including which are active and who’s on the account.
- Copies of any leases, if the home has tenants or was ever rented.
- Homeowner’s insurance policy information, including the carrier and policy number.
- Any liens, judgments, or open permits tied to the property.
- A one-page relocation timeline stating your target closing date and the date you need possession released.
Scan everything as PDFs, not photos, and share them through a secure link or encrypted email rather than a group text thread. Investors who can verify your payoff amount and lien status on day one can issue a firm offer instead of a placeholder number pending “further review.”
Pro Tip: Put your relocation deadline in writing on page one of the packet. Investors treat a stated move-out date as a scheduling constraint, not a negotiating opening, and it often speeds up how fast they return a number.
How Do You Compare Multiple Cash Offers?
The offer with the biggest number on top isn’t automatically the one that puts the most money in your pocket, or the one that actually closes. Compare net-to-seller, not headline price.
Start by subtracting from each offer: any buyer credits, how closing costs get split, your mortgage or lien payoff, and any fees the buyer’s contract tucks into the fine print. A $195,000 offer with the buyer covering title fees can beat a $205,000 offer where you’re absorbing $12,000 in closing costs and a repair credit.
Then look past the number entirely:
- Has the buyer provided proof of funds from a bank or verified account, not just a text saying “I have cash”?
- Is there a financing contingency hiding in an otherwise “cash” offer?
- How long is the inspection period, and can the buyer walk after it with no penalty?
- Does the contract include assignment rights that let the buyer flip your contract to someone else before closing?
- Is the closing date firm, or written as “on or around”?
Reliability beats raw price for a relocating seller almost every time. A slightly lower offer with verified funds and no financing contingency is worth more than a higher one that might collapse two weeks before your moving truck arrives. Treat vague answers about who’s handling escrow, last-minute requests to change wiring instructions, or offers that only work through an unnamed “assignee” as reasons to walk away, not negotiate harder.
Timeline Expectations for Fast Closings (7 to 21 Days)
Most competing cash-offer closings land somewhere between 7 and 21 days from accepted offer to keys handed over, depending on title work, payoff coordination, and how quickly you can vacate. The fastest closings usually happen within about a week when there’s no mortgage payoff to coordinate, no tenants to notify, and a title company that already has your documents in hand.
Three separate dates matter here, and sellers often blur them together: the date you accept an offer, the date the sale legally closes, and the date you actually hand over possession. You can close on paper and still negotiate a few extra days of occupancy if your move-out date lands after closing, but that only works if it’s written into the purchase agreement, per the CFPB’s closing guidance.
A realistic week-by-week expectation looks like this: days 1 to 3 for requesting and comparing offers, days 4 to 7 for title search and payoff verification, and days 8 to 21 for final walkthrough, signing, and fund disbursement. Homes with clean titles and no liens tend to sit at the front of that range. Homes with an open estate, unresolved permits, or multiple heirs on the deed usually land closer to three weeks, sometimes longer if probate court is involved.
Build a buffer into your own moving plans. Committing movers or a new lease to a closing date before title work confirms clean ownership is a common, avoidable mistake.
Michigan Seller Disclosure Requirements You Can’t Skip
Selling as-is does not mean you skip disclosure. Michigan’s Seller Disclosure Act, commonly cited as Act 92, requires sellers of one to four unit residential properties to provide a written disclosure statement before a binding purchase agreement is signed, with a handful of statutory exceptions, according to the Michigan Compiled Laws text of Act 92.
That statement covers known defects in the roof, foundation, plumbing, electrical systems, and more. “As-is” tells a buyer you won’t fix anything they find. It doesn’t excuse you from telling them what you already know is broken. Those are two different legal concepts, and conflating them is one of the more common mistakes relocating sellers make when they’re rushing to close.
Timing matters as much as content. If you deliver the disclosure late, a buyer may be able to terminate the purchase agreement within a specific window after receiving it, per Act 92’s own language. That’s a real risk on a tight relocation timeline: a late or incomplete disclosure form can hand your buyer a legal exit ramp right when you thought the deal was locked. Fill it out honestly and hand it over before you sign anything binding, and have your closing contact confirm it’s been received and acknowledged.
Transfer Tax and the Property Transfer Affidavit: What You’ll File
Two separate paperwork obligations show up at closing, and sellers who’ve never sold a home before often confuse them.
The first is Michigan’s State Real Estate Transfer Tax, commonly called SRETT. It applies to most conveyances of real property unless a statutory exemption applies, and your settlement agent should confirm which exemptions, if any, apply to your situation, according to the Michigan Department of Treasury’s SRETT guidance. SRETT is generally the seller’s responsibility at closing, so ask your title company to show you the exact allocation on your closing statement rather than assuming a flat rate applies to your sale.
The second is the Property Transfer Affidavit, form L-4260. This one falls on the buyer, not you, but it’s worth understanding because it affects how quickly the new owner’s assessment gets updated. The new owner must file it with the local assessor within 45 days of the transfer, and failing to do so can trigger penalties, per the City of Detroit’s L-4260 form instructions. If you’re staying in Michigan and buying another property, you’ll be the one filing this on your next purchase, so it’s worth knowing the deadline exists.
Neither of these should slow down a fast closing if your title company handles them routinely, which most Detroit-area settlement agents do.
Wire Fraud and Closing Fund Safety Steps
Fast closings are a favorite target for scammers, because urgency makes people skip the verification step they’d normally take. The Consumer Financial Protection Bureau warns that closing-time wiring scams are common enough that every seller should treat wiring instructions with real suspicion, especially any that arrive by email.
Here’s the pattern scammers use: they intercept or spoof an email thread from your title company, then send “updated” wiring instructions a day or two before closing. The email looks legitimate. The account number isn’t yours, and once funds move, they’re often gone for good.
Protect yourself with a few habits that cost nothing and take five minutes:
- Call your title company or closing agent using a phone number you looked up independently, not one from an email signature.
- Verify wiring instructions by phone before sending or expecting any funds, every single time, even if you’ve worked with the same company before.
- Treat any last-minute change to account numbers or routing details as a red flag, not routine, per CFPB’s closing checklist.
- Ask upfront who specifically will handle your closing and confirm that person’s direct contact information before the closing date arrives.
Name your closing contact in writing early in the process. It sounds like overkill until the week your relocation timeline gets tight and you’re tempted to trust whatever email lands in your inbox.
What Does Selling a House in Detroit Actually Cost?
A traditional listing carries more line items than most first-time sellers expect, and they add up fast on a home that needs work before it hits the market.
| Cost category | Traditional agent sale | As-is cash sale |
|---|---|---|
| Agent commission | Typically 5 to 6% of sale price, split between listing and buyer’s agents | None |
| Repairs and prep | Varies widely; often several thousand dollars for a dated Detroit-area home | None required |
| Staging and cleaning | Seller expense, ongoing during listing period | None required |
| SRETT | Seller-paid, subject to exemptions | Seller-paid, subject to exemptions |
| Title and closing fees | Negotiated, often split | Typically negotiated the same way |
| Capital gains exposure | Possible, but many sellers qualify for exclusion | Same exclusion rules apply |
Repairs are where relocating sellers get burned most often. A buyer’s inspector flags a roof issue or knob-and-tube wiring, the buyer asks for a credit or walks, and you’re back to square one with weeks gone and your moving date unchanged. Selling as-is removes that entire category of risk and cost, though the trade-off shows up as a lower headline offer than a fully renovated home might fetch on the open market.
On the tax side, homeowners who’ve lived in the property as a primary residence generally qualify to exclude up to $250,000 of gain ($500,000 for married couples filing jointly) under the IRS home-sale exclusion rules, though eligibility depends on ownership and use tests specific to your situation. Talk to a tax professional before you assume you qualify.
Do You Need to Stage a House You’re Selling As-Is?
Not the way a traditional listing does, no. If you’re taking competing cash offers from investors, elaborate staging and curb-appeal projects are largely wasted money, because investors are pricing the property based on condition and comparable sales, not how well your living room photographs.
That said, a few low-cost steps make a real difference in how quickly and accurately investors can bid.
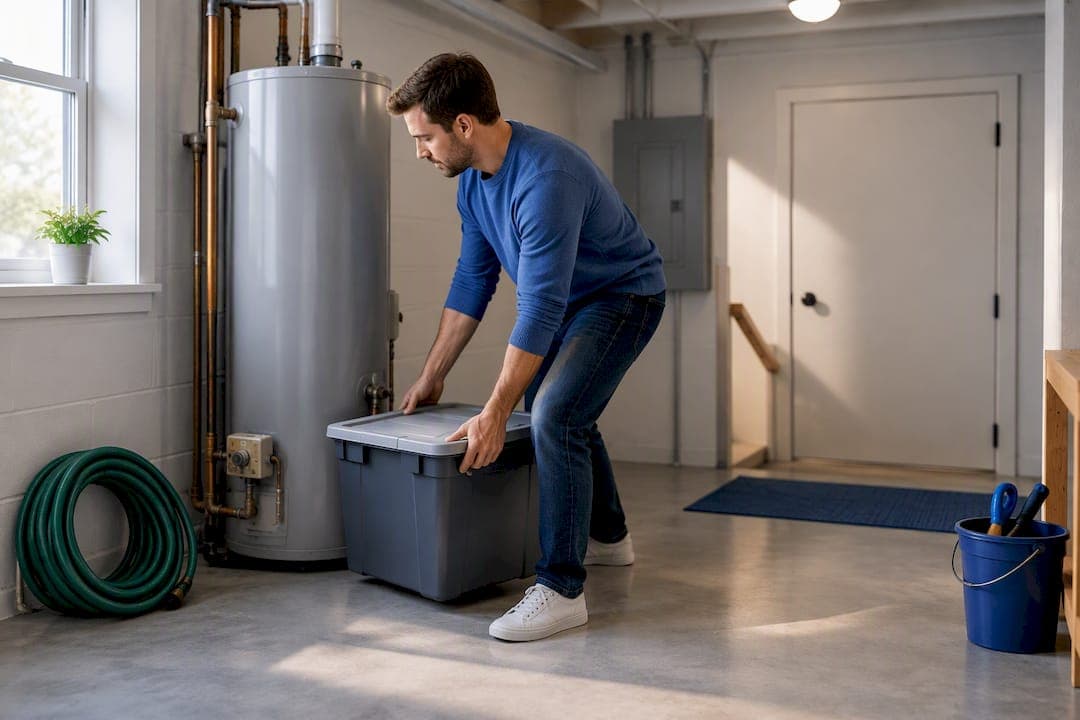
Clear pathways to the electrical panel, water heater, and crawl space or basement access points before you request offers. Investors or their contractors often want a quick walkthrough, and a home that’s hard to inspect gets a more conservative, hedge-your-bets number. Remove obvious clutter from rooms so square footage and layout are easy to assess. Fix anything genuinely dangerous, like an exposed wire or a broken step, mainly for your own liability during walkthroughs, not because it’ll change the offer significantly.
Skip the paint, skip the new flooring, skip the landscaping overhaul. On a relocation timeline, every dollar and every day spent prepping a house you’re selling as-is is a dollar and a day you don’t get back, and it rarely moves an investor’s number the way it would move a retail buyer’s.
How Detroit’s Market Trends Affect Your Price and Speed
Detroit’s housing market has run hotter on the investor side than many suburban Michigan markets, largely because of the concentration of older housing stock, more inherited and probate sales, and a deep bench of local buyers who specialize in properties needing work. That’s good news if you’re selling as-is on a deadline: demand from that buyer pool doesn’t dry up the way retail buyer demand can when interest rates rise.
Seasonal timing still matters. Spring and early summer typically bring more competing buyers into any Michigan market, which can mean stronger bids even on an as-is investor sale. Winter sales in Madison Heights and greater Detroit tend to move slightly slower simply because fewer buyers are actively shopping, though a serious cash-offer marketplace with a stable pool of local investors is far less seasonal than the retail listing market.
Neighborhood-level condition matters more than city-wide averages. A block with several recently renovated flips will pull stronger investor interest than a block that’s mostly still distressed, even within the same Detroit zip code. If you’re not sure how your specific street compares, that’s a fair question to ask any investor who bids, since a serious buyer should be able to point to comparable recent sales near you.
Should You Use a Real Estate Agent for a Detroit Relocation?
If your timeline allows for a traditional listing, and you’re not under a hard relocation deadline, an agent who specifically works Detroit relocation sales can be worth the commission. The skill you want isn’t generic real estate experience. It’s someone who’s closed deals on a compressed timeline before and knows which Detroit-area title companies move fast.
Ask any agent you’re considering three specific questions: how many relocation sales have they closed in the past year, what’s their average days-to-close on those specific deals, and can they name a title company they trust to turn around a payoff and lien search in under a week. Vague answers to any of those three are a sign they’re used to normal-timeline listings, not relocation deadlines.
The honest trade-off is this: an agent can sometimes get you a higher sale price on the open market, but that process typically takes 30 to 90 days even in a strong market, plus the commission, plus repair negotiations after inspection. If your relocation date is fixed and close, that math often doesn’t work, which is exactly the situation a competing cash-offer marketplace is built to solve instead.
Legal Considerations Specific to a Detroit Relocation Sale
Beyond disclosure and transfer tax, a few Detroit-specific legal wrinkles catch relocating sellers off guard.
If the property has open building permits from a past renovation, the city may flag them during title work, and clearing them can take longer than a normal closing timeline allows. Check with the City of Detroit’s Buildings, Safety Engineering and Environmental Department early if you suspect any unpermitted work happened while you owned the home.
If you inherited the property or hold it jointly with siblings or other heirs, every named owner on the deed generally needs to sign closing documents, which can be the single biggest source of delay on an otherwise fast sale. Sort out who’s authorized to sign before you request offers, not after you’ve accepted one.
And if the home has tenants, Michigan landlord-tenant law requires proper notice before a sale can force a lease termination, so factor that timeline into your relocation plan rather than assuming a cash sale erases existing lease obligations automatically.
Coordinating Your Home Sale with Your Moving Timeline
Work backward from your relocation date, not forward from your closing date. If your new job starts on a fixed date in a different state, that date drives everything else, including when you should request your first round of offers.
A reasonable sequence looks like this: request offers and compare net sheets in week one, accept an offer and begin title work in week two, and target closing sometime between week two and week four depending on how clean the title is. Book your movers only after you have a signed purchase agreement with a firm closing date, not before, since committing to a moving truck on a date that later slips is one of the more stressful and avoidable mistakes relocating sellers make.
If your move-out date and your closing date don’t line up, negotiate a short post-closing occupancy period in writing, specifying the exact number of days and any daily fee involved, per the CFPB’s guidance on closing expectations. A verbal agreement to “stay a few extra days” is not something you want to rely on once the new owner legally holds the deed.
Keep utilities active through your actual move-out date, forward your mail early, and confirm with your buyer or their title company exactly when keys and garage remotes need to change hands. These sound like small details until the week of your move, when every hour matters.
The Practical Lessons Relocation Sellers Learn the Hard Way
The highest offer on the table is often the least reliable one. A bid that’s $10,000 higher but carries a financing contingency, a vague inspection period, or an unnamed assignee behind it can collapse two weeks before your movers show up, while a slightly lower verified-funds offer closes exactly on schedule.
Ask for a seller net sheet from every serious bidder, not just a headline number. Name your closing contact early, in writing, and confirm that contact independently rather than trusting whatever number appears in an email signature. Keep the property accessible for reasonable due diligence even on an as-is sale. Refusing walkthroughs or slow-walking document requests is one of the fastest ways to turn a promised 7-day closing into a month-long standoff, since Michigan’s own transfer-tax guidance assumes reasonable cooperation between parties to keep a transaction moving.
If you negotiate any post-closing occupancy, put it in writing with specific dates. A handshake agreement about “a few extra days” is the kind of thing that feels fine until moving week arrives and suddenly it isn’t.
— Bryan
Get Multiple Cash Offers Fast Through Housegoodbye
Housegoodbye is the direct alternative to juggling a single lowball buyer or paying an agent’s commission on a timeline you don’t control. Instead of one investor naming a price and hoping you accept, Housegoodbye puts your Madison Heights or Detroit-area home in front of multiple vetted local investors who compete for it, so you see real numbers side by side and pick the strongest net offer, not just the biggest headline figure.
The process starts with your seller packet, which is the same document set covered earlier in this article. You share it once, investors bid, you compare net sheets, and you pick a buyer and a closing date that actually matches your relocation timeline, often in as little as 7 days according to fast closings. No repairs, no showings, no agent fees eating into your proceeds.
If your moving date is already set, request your competing cash offers today, or start with the fast-sale process built for Madison Heights sellers to see how quickly a firm offer can land in your inbox.
Sources
A few government resources are worth reading directly, not just secondhand. IRS Publication 523 explains whether your sale qualifies for the home-sale gain exclusion. The Michigan Seller Disclosure Act, Act 92, spells out exactly what you must disclose and when. Michigan’s SRETT guidance covers your transfer-tax exposure and exemptions. The Property Transfer Affidavit (L-4260) governs post-closing filing deadlines. And the CFPB’s closing-scam guidance could save your closing funds outright.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
- IRS Publication 523, Selling Your Home
- Michigan Compiled Laws — Act 92 (Seller Disclosure Act)
- Property Transfer Affidavit (L-4260) — City of Detroit
FAQ
How Fast Can I Actually Close on a Relocation Sale in Detroit?
Most competing cash-offer closings take between 7 and 21 days from accepted offer to keys handed over, with the fastest deals happening when there’s no mortgage payoff or tenant notice to coordinate. Fast closings can be as little as 7 days for qualifying homes.
Do I Still Need to Disclose Defects on an As-Is Sale?
Yes. Michigan’s Act 92 requires a written disclosure statement before a binding purchase agreement, and selling as-is only means the buyer won’t ask you to fix anything, not that you can skip telling them what’s wrong.
Who Pays Michigan’s Transfer Tax When I Sell?
The State Real Estate Transfer Tax (SRETT) is typically the seller’s responsibility unless a statutory exemption applies, and your settlement agent should confirm the exact allocation, according to Michigan Treasury’s SRETT guidance.
How Do I Avoid Wire Fraud During a Fast Closing?
Verify any wiring instructions by phone using a number you look up independently, never one from an email, since the CFPB warns closing-time scams commonly target sellers moving quickly.
Does Housegoodbye Charge Fees to Get Cash Offers?
Housegoodbye’s current pricing details are available directly on its site, and the platform’s core positioning is competing investor offers without agent commissions eating into your proceeds. Check the competing cash offers page for the latest details on your specific property.